In a landmark shift for the Peruvian financial landscape, the Superintendency of Banking, Insurance, and Private Pension Funds (SBS) has officially overhauled the mechanics of retirement savings. As of Thursday, September 24, contributors to the Private Pension System (SPP) are no longer confined to traditional banking channels. By incorporating digital wallets, mobile applications, and correspondent agents into the regulatory framework, the SBS is signaling a definitive move toward a more inclusive, accessible, and digitized pension infrastructure.
This regulatory update, formalized in the official gazette El Peruano, marks the conclusion of a rigorous public consultation process that began in mid-2024. For millions of Peruvian workers—particularly independent contractors and those operating within the informal or gig economy—the move represents a significant reduction in friction when planning for their financial future.
The Core Transformation: Moving Beyond Traditional Banking
Historically, the process of contributing to an AFP (Administradora de Fondos de Pensiones) has been rigid. For employees, the burden of payment rested largely on the employer, who would process deductions through established banking gateways. For independent workers, the process often involved manual bank transfers or physical visits to financial institutions—tasks that are frequently time-consuming and prone to administrative delays.
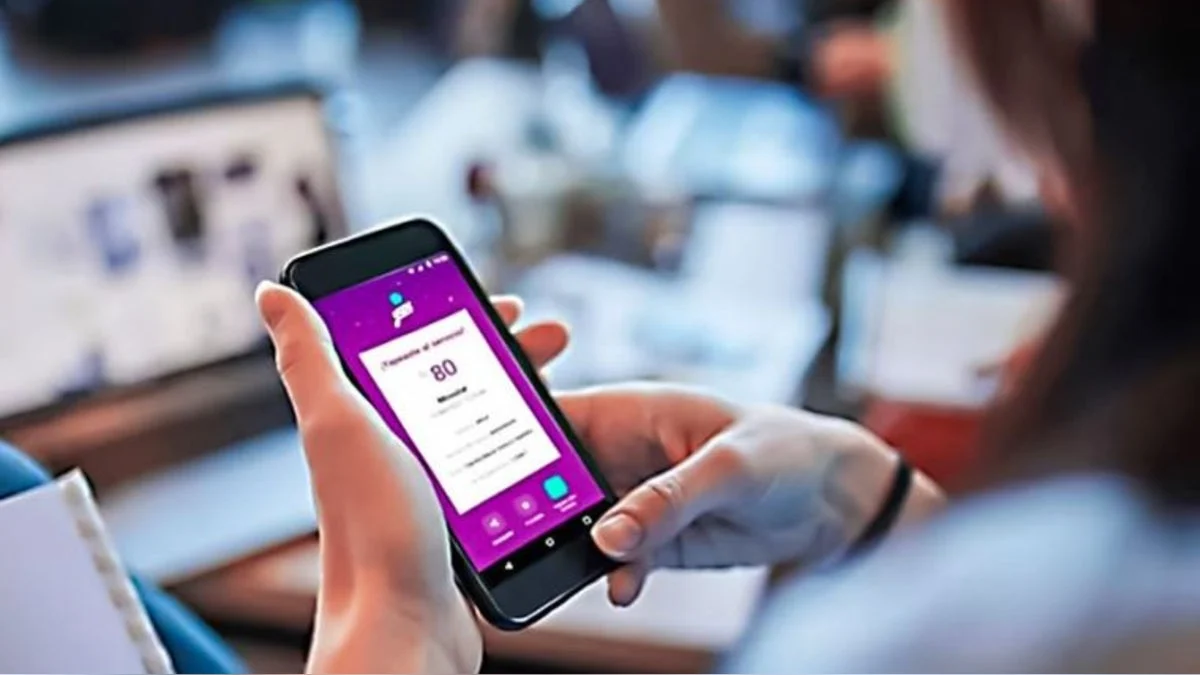
The new regulation democratizes this process. Under the updated rules, AFP contributors can utilize digital wallets (such as Yape or Plin), third-party payment applications, and local correspondent agents to make their monthly contributions.
Key Changes at a Glance:
- Diversification of Channels: Contributions are no longer tethered solely to bank transfers or physical office visits.
- The Rise of "Intermediary Institutions": The regulation introduces a new legal entity class known as "intermediary institutions." These entities—ranging from authorized payment service providers to financial technology (fintech) firms—act as the bridge between the user and the AFP.
- Operational Agility: The move aims to harmonize the pension system with the rapid digitization of Peru’s retail payment landscape, where mobile-first financial behavior is increasingly the norm.
Chronology of a Regulatory Shift
The transition to a digital-first contribution model was not an overnight decision. It was the result of a deliberate, data-driven policy cycle initiated by the SBS to address stagnant contribution rates and administrative barriers.
- June 2024: The Public Consultation Phase: The SBS introduced a draft proposal to the public, inviting feedback from industry experts, fintech stakeholders, and the general public. The primary objective was to "flexibilize" the collection mechanism, moving away from archaic payment structures that hindered independent workers.
- August 2024: Synthesis and Refinement: During this period, the SBS processed comments regarding security, transaction fees, and data reconciliation. The feedback emphasized the need for strict protocols to ensure that digital payments are credited accurately and that no capital is lost during the digital transfer process.
- September 2024: Official Enactment: Following the final review, the regulation was published in El Peruano. The transition period was set to culminate on September 24, making the new rules legally binding for all AFPs and their newly designated intermediary institutions.
Supporting Data and Technical Framework
The success of this initiative hinges on the technical robustness of the "intermediary institutions." These entities must be registered under the national payment system rules and maintain strict contractual agreements with the AFPs they serve.
The Financial Safety Net
One of the most critical aspects of the new regulation is the protection of the contributor’s funds. The SBS has implemented stringent requirements to ensure that the transition from a digital wallet to a pension account is seamless and secure:
- Reconciliation Mandate: AFPs are now legally responsible for the "entire journey" of the money. This includes the validation, transmission, and registration of every cent.
- Strict Timelines: If an intermediary institution collects a contribution, it is legally obligated to deposit that sum into the AFP’s account no later than the second business day following the transaction. This minimizes the "float" time where money could be lost or misused.
- The "Zero-Loss" Policy: Should an intermediary charge a service fee, the regulation mandates that the AFP must compensate for this charge to ensure the full value intended by the contributor reaches their pension fund.
- Currency of Value: The regulation ensures that the "unit value" (the value of the pension share) is fixed based on the date of the payment, not the date of final processing. If a contributor initiates a payment on October 10th, they are protected by the share price of that specific day, regardless of administrative lag.
Official Responses and Strategic Vision
The SBS has been vocal about its strategic intent behind this move. By allowing for "more direct, rapid, and accessible" payments, the regulator is acknowledging that the previous system was a deterrent to voluntary contributions.
"We are moving toward a frictionless retirement system," an SBS spokesperson noted during the public consultation phase. "If we want a robust private pension system, we must meet the workers where they are: on their smartphones."
Industry analysts have praised the move as a long-overdue modernization. For the AFPs, this change is not merely about convenience; it is a vital strategy for expanding their reach. By lowering the barrier to entry, AFPs expect to see an uptick in voluntary contributions from independent workers who previously viewed the banking process as too cumbersome.
Implications for the Future of Pensions
The integration of digital wallets into the pension system carries profound implications for the future of the Peruvian economy.
1. Increased Financial Inclusion
By leveraging existing digital wallets, the SBS is tapping into a population that might be "unbanked" but is highly active in the digital economy. This inclusion is expected to bring a significant number of independent workers into the formal social security net, eventually reducing the long-term fiscal burden on the state by ensuring more citizens have private savings.
2. Streamlining the Gig Economy
As Peru’s gig economy continues to expand—with delivery drivers, freelancers, and independent service providers making up a growing portion of the workforce—the ability to pay a "pension contribution" in the same way one pays for a utility bill or a food delivery will likely improve long-term retirement security for this demographic.
3. Technological Synergy
The regulation forces a level of interoperability between AFPs and the fintech sector. This will likely lead to further innovation, such as automated contribution plans, where an app could theoretically round up small purchases or deduct a small, recurring percentage of income to automatically fund a pension account.
4. Risk Mitigation and Oversight
While the convenience is high, the SBS remains vigilant. By requiring all intermediaries to have formal agreements with AFPs, the regulator ensures that the "wild west" of unregulated payments does not touch the national pension pool. Every transaction remains traceable, audit-ready, and compliant with the strict oversight standards of the Superintendency.
Conclusion
The transition toward digital pension contributions marks a turning point for Peru. By embracing the reality of modern payment technologies, the SBS has effectively bridged the gap between the traditional retirement industry and the fast-paced digital consumer. As of September 24, 2024, the path to a secure retirement is literally at the fingertips of every Peruvian worker.
While the implementation will require ongoing monitoring to ensure that intermediary institutions maintain the high security standards demanded by the SBS, the fundamental shift toward accessibility is a positive step. It empowers the worker, creates a more resilient pension system, and sets a standard for financial digitization in the region. Whether through a smartphone tap at a corner store or a transfer from a digital wallet, the act of saving for the future has finally been brought into the 21st century.