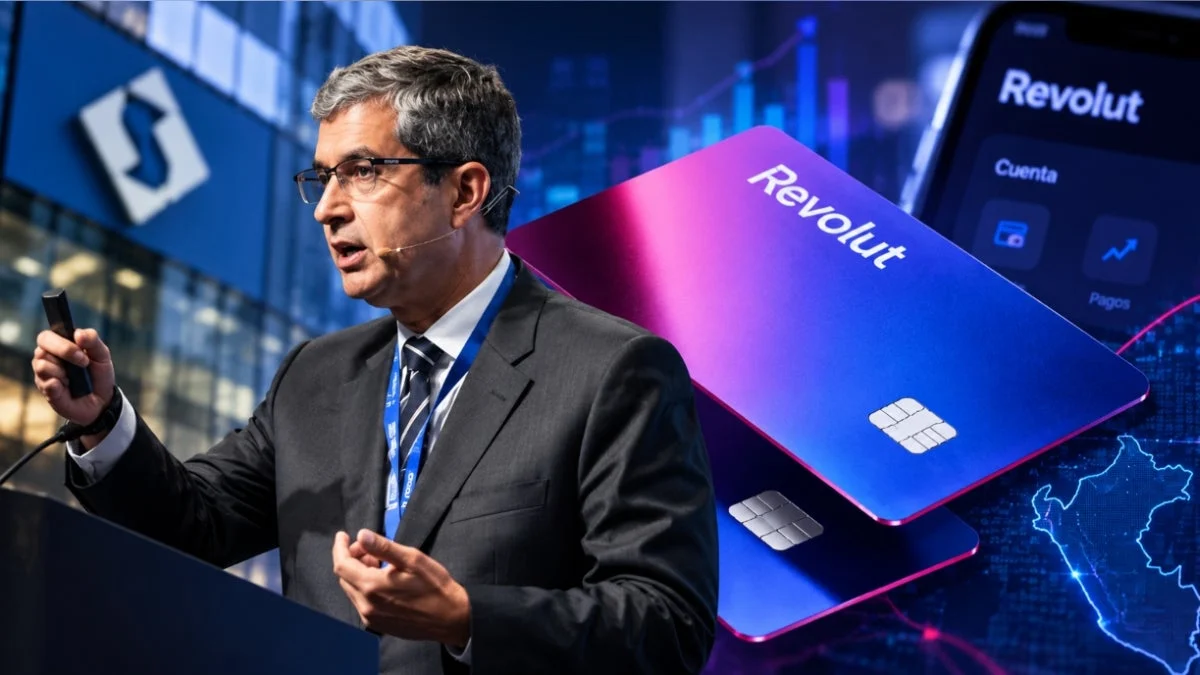
The global financial technology revolution is poised to reach a significant milestone in Peru. Revolut, the British-based global neobank, is currently navigating the final stages of regulatory approval to launch its 100% digital banking operations in the Andean nation. While the company has already secured its initial "organization license" from the Superintendency of Banking, Insurance, and Private Pension Funds (SBS), the timeline for its official debut remains firmly in the hands of the fintech giant.
As the Peruvian financial ecosystem braces for this transformation, regulators and industry analysts are closely monitoring the progress. For the Peruvian consumer, the arrival of a global digital powerhouse represents a potential shift in how banking services are accessed, managed, and perceived.
Main Facts: The Current Status of Revolut’s Expansion
The entry of Revolut into Peru is not merely a corporate expansion; it is a signal of the country’s growing attractiveness as a hub for financial innovation. Sergio Espinosa, the Superintendent of the SBS, confirmed in recent statements that the regulatory body has already completed the first and most critical stage of the process.
The "license of organization" granted to Revolut signifies that the SBS has vetted the company’s business model, its leadership team, and the capitalization required to sustain operations in a competitive market. However, holding this license does not grant the right to operate banking services immediately. Revolut is currently in a "construction phase," where it must establish the backbone of its local presence. This includes the deployment of IT infrastructure, the recruitment and training of local personnel, the establishment of internal accounting systems, and the finalization of operational protocols that comply with Peruvian financial regulations.
"They are in the process," Espinosa noted. "They have stated they intend to conclude this phase during 2027. We hope it happens as early as possible—perhaps in the first months of the year rather than waiting until the end—but that decision ultimately rests with them."
Chronology: A Path Toward Digital Integration
The road to a fully operational digital bank in Peru is paved with rigorous regulatory scrutiny. The process, which began with initial filings and informal discussions, has moved through the following milestones:
- Initial Market Evaluation: Revolut executives, led by CEO Julien Labrot, identified Peru as a priority market based on its macroeconomic stability, growth potential, and the increasing digital literacy of its population.
- The Application Phase: Revolut formally submitted its application to the SBS, initiating a comprehensive review of its global business model and its suitability to operate under the Peruvian regulatory framework.
- Approval of Organization License: Several months ago, the SBS granted the organization license, authorizing the company to begin building its local structure.
- Operational Readiness (Current Phase): Revolut is currently engaged in the "build-out" phase, where it must translate its global technical capabilities into a localized, compliant banking architecture.
- Final Inspection (Pending): Once Revolut declares its readiness, the SBS will conduct a final, on-site inspection of its systems and facilities before issuing the definitive operating license.
Official Responses and Strategic Challenges
The SBS, under Sergio Espinosa, has adopted a balanced approach. While the regulator is keen to see new players enter the market to drive efficiency and competition, it maintains a strict adherence to security and consumer protection standards.
Espinosa highlighted that Revolut’s entry is happening alongside its massive, multi-continental expansion. This global strategy inherently creates a "pressure on resources." By entering multiple markets across the Americas and beyond simultaneously, the company must juggle its human and technical capital across different time zones and regulatory regimes.
"We understand that they are managing a global expansion," Espinosa remarked. "However, our role is to facilitate an environment where they can operate as soon as they are prepared to meet our standards."
On the company side, the narrative remains one of calculated, high-standard growth. Julien Labrot has emphasized that Revolut does not enter markets lightly. The firm employs a "super-strict" evaluation process, weighing potential growth against the quality of local institutions. For Revolut, Peru is not just another dot on the map, but a strategic node in its Latin American growth story.
Implications: A New Era for Peruvian Banking
The entry of a "pure-play" digital bank like Revolut forces a mirror to be held up to the existing financial institutions in Peru. The local market is already familiar with digital banking—most major Peruvian banks have robust mobile applications, and the rise of digital wallets has changed how everyday transactions are handled. However, Revolut brings a different value proposition: a borderless, multi-currency, and highly agile platform that has disrupted traditional banking in Europe and beyond.
1. Competitive Pressure on Incumbents
The traditional banking sector will likely face pressure to lower costs and improve user experience. While the "big players" in Peru have invested heavily in digital channels, Revolut’s native digital architecture may offer a level of fluidity that legacy systems struggle to match.
2. The Challenge for Microfinance and Cajas
Perhaps the most significant impact will be felt by municipal savings banks (cajas municipales) and other microfinance institutions. According to the SBS, the competitive landscape is shifting rapidly. These smaller, often more regional institutions are currently in a race to accelerate their digital transformation. The development of a collective digital wallet for the cajas is a direct response to this changing tide.
"The main challenge lies with the municipal banks and other microfinance entities," Espinosa explained. "They must accelerate their digitalization processes to remain relevant to a younger, more digitally native consumer base."
3. Financial Inclusion and Innovation
Revolut’s arrival may also catalyze financial inclusion. By offering a platform that is accessible, low-friction, and potentially cheaper than traditional accounts, the neobank could attract segments of the population that have been historically underserved by the formal banking system. If successful, this could create a ripple effect, forcing traditional institutions to innovate their products to retain their customer base.
Supporting Data: Why Peru?
Why has a company with the global reach of Revolut chosen Peru? The answer lies in a confluence of factors:
- Digital Adoption Rates: Over the past five years, Peru has seen an explosion in the usage of digital financial services, accelerated by the COVID-19 pandemic and the subsequent adoption of interoperable payment systems.
- Institutional Stability: Despite political volatility, the Peruvian financial system has remained robust, with the SBS recognized globally for its strict, prudential supervision.
- The "Yape" Effect: The success of digital wallets in Peru has demonstrated that the Peruvian consumer is ready for digital-first solutions. Revolut views this as a "pre-warmed" market where users already understand the mechanics of app-based banking.
- Untapped Potential: While the top-tier banks hold significant market share, there remains a vast demographic—particularly among the youth—that is actively seeking better, more globalized financial tools.
Conclusion: The Road Ahead
As 2027 approaches, the financial sector in Peru is poised for a significant transformation. The arrival of Revolut is not merely the arrival of a new competitor; it is an endorsement of the maturation of the Peruvian financial market.
Whether Revolut launches in the early months of 2027 or towards the end of the year, the "digital bell" has already rung. For the Peruvian consumer, the future of banking will be defined by agility, transparency, and a global reach that was, until recently, beyond the grasp of the average user. For the regulators, the task remains clear: to ensure that this influx of innovation is matched by the necessary safeguards to protect the integrity of the nation’s financial system.
As the British giant finalizes its internal preparations, the rest of the industry watches with a mix of anticipation and strategic urgency. The race to digital dominance in Peru has entered its final, most critical lap.