The landscape of labor economics in Peru underwent a significant shift this October, as the adjustment to the Remuneración Mínima Vital (RMV)—the national minimum wage—triggered a ripple effect across the country’s social security framework. Specifically, the contribution threshold for the Sistema Nacional de Pensiones (SNP), managed by the Oficina de Normalización Previsional (ONP), has been recalibrated to reflect the new economic baseline.
For millions of workers and thousands of independent professionals, understanding these changes is vital for maintaining coverage and ensuring future retirement security. This report breaks down the mechanics of the new contribution rates, the implications for different labor sectors, and the logistical procedures for meeting these updated obligations.
Main Facts: The New Contribution Baseline
Effective October 1, the RMV in Peru has been adjusted to S/ 1,230. Because the mandatory contribution to the ONP is fixed at 13% of a worker’s declared monthly income, the floor for social security payments has necessarily shifted.
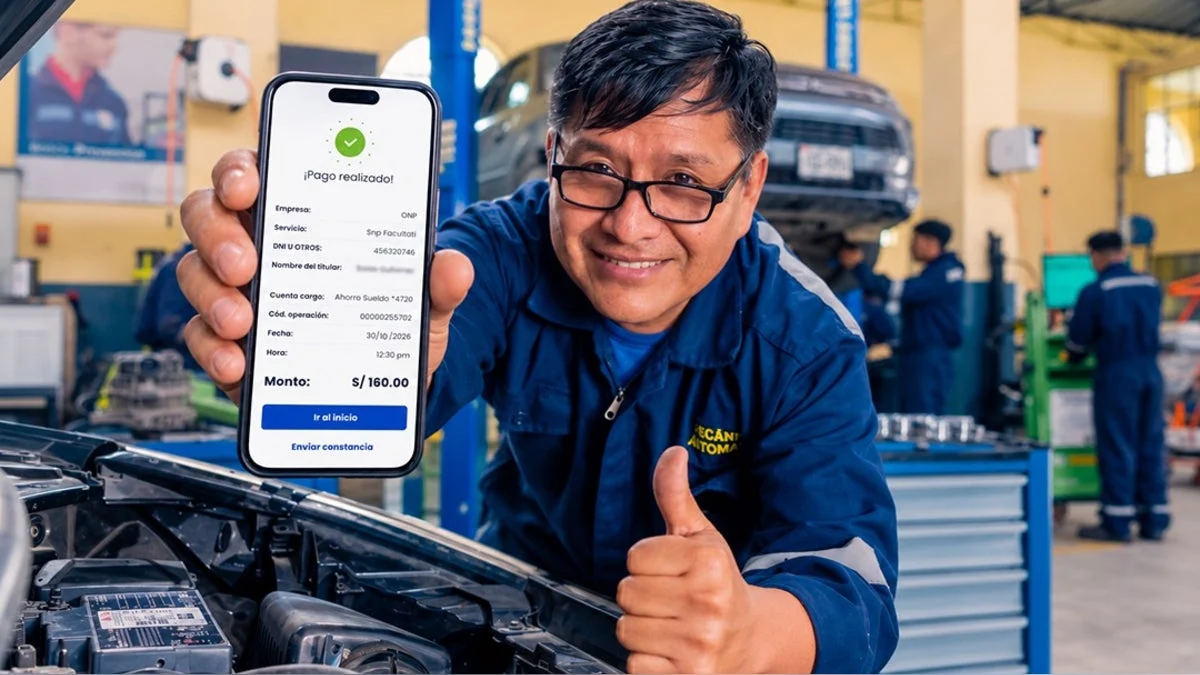
Previously, with the minimum wage set at lower levels, the minimum monthly contribution stood at S/ 147. Following the latest policy implementation, this minimum contribution has risen to S/ 160. It is crucial to note that this is not an arbitrary increase, but a direct mathematical consequence of the 13% rate applied to the new minimum wage.
Whether an individual is a formal employee or an independent contractor, the principle remains the same: the contribution is proportional to the income declared. However, for those earning exactly the minimum wage or those choosing to contribute based on the minimum threshold, the S/ 160 figure represents the new standard for monthly compliance.
Chronology of the Adjustment
The road to this change began with government deliberations on inflationary pressures and the purchasing power of the average Peruvian worker.
- Pre-October 2024: The minimum wage remained at a level that dictated a monthly ONP contribution of S/ 147 for those earning the minimum base.
- October 1, 2024: The new RMV of S/ 1,230 came into effect. Consequently, the minimum ONP contribution automatically adjusted to S/ 160.
- The Payment Window: The ONP mandates that contributions for a specific month must be paid by the last day of the following month. Therefore, the first payment reflecting the new S/ 160 rate (for the month of October) is due no later than November 30.
- Ongoing Compliance: Moving forward, all monthly contributions must reflect this updated minimum, provided the worker’s income level warrants the minimum threshold calculation.
Supporting Data: Understanding the 13% Model
The ONP operates on a solidarity-based "pay-as-you-go" system. Unlike the Private Pension System (AFP), where funds are held in individual capitalization accounts, the ONP pools contributions to fund the pensions of current retirees.
The Mathematics of Contributions
The 13% figure is a flat-rate deduction applied to the total remunerative income. For a worker earning the minimum wage:
- Old Calculation: S/ 1,130 (approx. old base) × 0.13 = S/ 147.
- New Calculation: S/ 1,230 (new base) × 0.13 = S/ 159.9, rounded to S/ 160.
Target Demographics
While millions of dependent workers see this adjustment automatically reflected in their pay stubs via payroll processing, the ONP has specifically highlighted the situation for its 22,239 independent affiliates. Unlike employees whose taxes and social security are handled by Human Resources departments, independent workers are responsible for their own voluntary or mandatory contributions. This group faces the most significant administrative burden, as they must ensure their digital or physical payments are accurate and timely to avoid gaps in their contribution history.
Official Responses and Administrative Procedures
The ONP has issued comprehensive guidance to ensure that the transition to the new payment structure is seamless. Recognizing that independent workers are at higher risk of missing payments, the agency has streamlined its digital and physical payment channels.
Digital Payment Channels
The ONP encourages the use of digital platforms to ensure record-keeping accuracy and ease of access:
- Interbank Negocios: Through the digital wallet and banking platform, independent contractors can make their monthly payments efficiently.
- SUNAT Operations Online: The "Operaciones en línea" platform of the tax authority remains a preferred channel. Notably, the ONP has confirmed that taxpayers do not need a "Clave SOL" to perform this specific transaction, reducing barriers to entry for smaller independent contributors.
Physical Payment Channels
For those who prefer traditional methods or lack access to robust digital banking, the ONP maintains a network of physical payment points:
- Interbank Agents: By providing the service code 0600203, the affiliate’s DNI (national identity document), and the specified amount (S/ 160), payments can be processed instantly.
- Banco de la Nación: Standard teller services remain available. Affiliates must provide their DNI, the month of the contribution, and the amount due.
The agency emphasizes that for both channels, accuracy in entering the DNI is paramount. Any error in the identification number could result in the payment being misallocated, potentially leading to a "contribution gap" in the worker’s history, which could complicate future pension applications.
Implications: The Long-Term View
The increase in the minimum contribution is more than just a logistical adjustment; it carries significant implications for the Peruvian labor market and the social security system.
For the Worker
While an increase of S/ 13 per month may seem marginal to some, for low-income workers, it represents a change in monthly disposable income. However, the long-term benefit of maintaining consistent, accurate contributions cannot be overstated. A robust history of contributions is the bedrock of future pension eligibility. By staying current with the S/ 160 minimum, workers ensure they meet the rigorous requirements set by the ONP for retirement, disability, and survivorship benefits.
For the Employer
For formal businesses, the change requires an update to payroll software and accounting systems. Employers are legally obligated to withhold the 13% and deposit it into the ONP accounts. Failure to update the payroll system to the new S/ 160 floor could result in administrative fines and legal liabilities, as the state views these contributions as protected employee benefits.
For the Social Security System
The adjustment is essential for the fiscal health of the ONP. By aligning contributions with the current cost of living (as measured by the RMV), the system maintains its ability to sustain current pension obligations. In an economy experiencing inflationary pressures, keeping the contribution base stagnant would erode the long-term viability of the fund.
The Risk of Informalization
A broader implication of increasing the cost of formal labor—even marginally—is the potential for businesses to shift toward informal hiring practices to avoid the associated social security costs. Policymakers will likely monitor whether the rise in the RMV and the corresponding rise in ONP contributions lead to a decrease in formal job creation or if the current economic growth is sufficient to absorb these costs.
Conclusion
The adjustment to the ONP minimum contribution to S/ 160 is a necessary procedural step following the government’s decision to increase the national minimum wage. While it requires a minor adjustment in monthly budgeting for workers and payroll management for employers, it serves as a critical component in ensuring the stability and integrity of the national pension system.
Independent workers, in particular, should take note of the November 30 deadline for the first payment of the new cycle. By utilizing the provided digital and physical channels—such as the SUNAT platform or Interbank agents—affiliates can ensure their retirement savings remain secure. As Peru continues to navigate the complexities of its economic recovery, these small, consistent actions remain the cornerstone of individual and collective financial security.