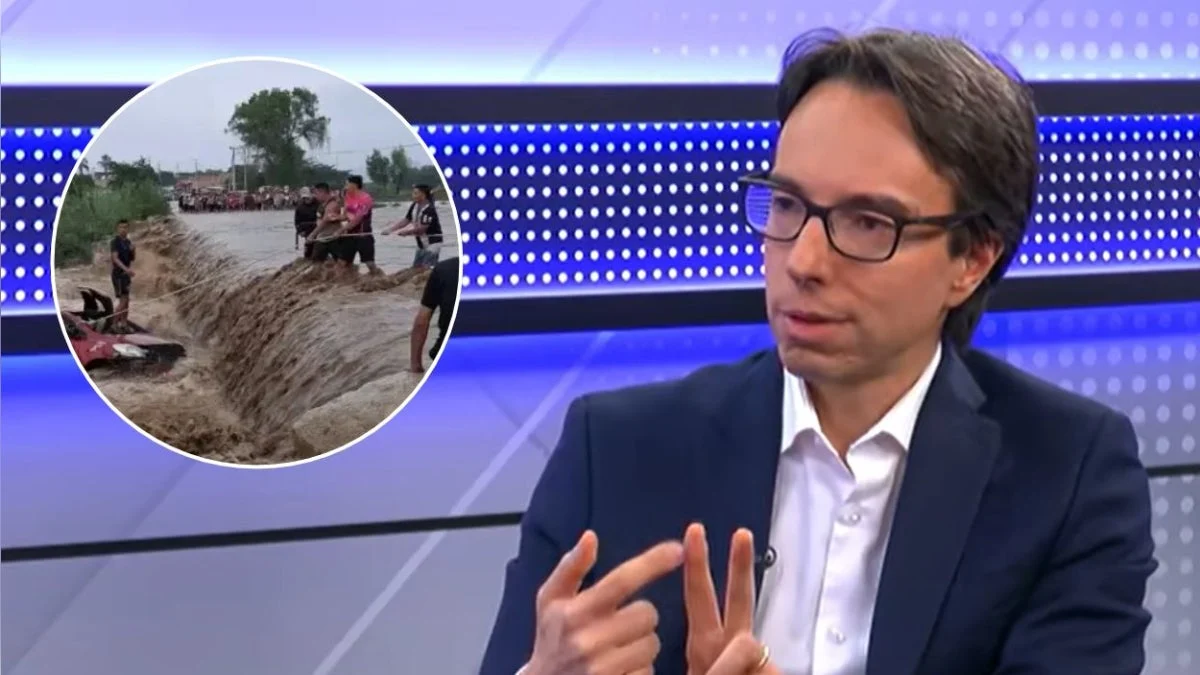
The Peruvian economy is bracing for a period of climatic turbulence that will test its resilience over the coming months. According to Daniel Velandia, Chief Economist at Credicorp Capital, the nation is set to face significant headwinds between November of this year and March 2027 due to the resurgence of the El Niño phenomenon. Despite this looming challenge, which threatens to dampen short-term growth, the country’s underlying macroeconomic fundamentals remain robust, leading to a projection of 3% growth for 2027 and a potential acceleration to 4.5% by 2028.
The Impending Climate Shock: Navigating the El Niño Threat
Daniel Velandia, speaking in an exclusive interview with RPP, emphasized that Peru stands as perhaps the most vulnerable nation in the region regarding climate-induced economic disruptions. "Between November and March, we are going to experience the most difficult months," Velandia noted. "We know that Peru is disproportionately affected by El Niño due to the high diversity of sectors that are sensitive to climatic volatility."
The primary economic transmission channels for this phenomenon include physical infrastructure damage, such as landslides and mudslides (huaicos), which impede the movement of goods and labor, thereby disrupting supply chains and manufacturing output. Historically, the agricultural, fishing, and non-primary manufacturing sectors bear the brunt of these disruptions. The risk is not merely in the output loss, but in the potential for temporary labor market contraction, particularly in rural areas where agriculture serves as a primary source of employment.
However, Velandia offers a measured perspective: this is a "negative shock," but one that should be viewed as temporary. The resilience demonstrated by the Peruvian economy following the 2023 iteration of El Niño serves as a precedent for a rapid recovery, provided the broader economic framework remains stable.
A Chronology of Economic Expectations (2026–2028)
The trajectory of the Peruvian economy over the next three years is characterized by a "V-shaped" recovery curve, albeit one hindered by the climate variable.
- Late 2026 – Early 2027 (The Contraction Phase): This period is defined by the peak of El Niño. Inflationary pressures from energy and food prices are expected to remain elevated, and industrial output will likely see a slowdown as logistics are hampered by climate-induced infrastructure failures.
- Second Semester 2027 (The Recovery Phase): As the weather patterns normalize, Credicorp Capital expects a rebound. The influence of strong private investment and sustained global demand for minerals should allow the economy to regain momentum.
- 2028 (The Expansion Phase): With the climate shock fully in the rearview mirror and several major mining projects reaching maturity, the economy is positioned to hit a growth ceiling of 4.5%. This shift marks a transition from managing crisis-induced volatility to capitalizing on structural productive capacity.
Supporting Data: Pillars of Resilience
Despite the gloomy short-term forecast for the next few months, the data suggests that Peru is far from a crisis. Credicorp Capital highlights several indicators that suggest the economy is primed for a swift recovery:
- Private Investment Dynamics: Private investment is expected to grow by approximately 14% throughout 2026, largely driven by the mining sector. Even more encouraging is the performance of non-mining and non-residential investment, which has shown growth rates exceeding 20%. For 2027, despite the El Niño effect, investment is projected to grow by 8%—a figure that would be considered strong in most emerging market contexts.
- Investor Confidence: Business sentiment regarding investment is currently at its highest level since 2010. This indicates that long-term capital allocation remains committed to Peru, notwithstanding the short-term political and environmental noise.
- Terms of Trade: Peru continues to benefit from favorable international prices for copper and gold. These high terms of trade act as a fiscal and monetary buffer, sustaining government revenue and supporting the national balance of payments.
- Household Consumption: Despite the anticipated dip in early 2027, household consumption is projected to grow between 2.5% and 3%. This suggests that the labor market, which remains relatively solid, is providing enough income stability to prevent a collapse in domestic demand.
Monetary Policy and Inflationary Pressures
Inflation remains a central concern for the Central Reserve Bank of Peru (BCRP). Credicorp Capital estimates that the year-end inflation rate for 2026 will close at approximately 4.7%. This pressure is driven by a confluence of global factors, including the high price of imported petroleum, and local factors, primarily the climate-related disruption to food supply chains.
Velandia anticipates that the BCRP will likely adopt a more hawkish stance in the coming months. "Today we have the expectation of a rate hike. I think there may be more than one," he stated. Projections suggest the reference interest rate could climb to 4.50%. However, this is not a static forecast; it is highly dependent on the evolution of international geopolitical conflicts and the degree to which energy prices stabilize.
Looking ahead to 2027, the inflationary picture becomes significantly brighter. As global supply chains adjust and the climate impact dissipates, inflation is expected to moderate toward 2.5%, aligning more closely with the BCRP’s long-term target range.
Structural Challenges: The Informal Economy
While the short-term focus is on climate and interest rates, Velandia emphasizes that the most critical hurdle to Peru’s long-term development is its high level of informality. The "informal trap" limits the government’s tax base and prevents millions of workers from accessing social security and productivity-enhancing training.
Velandia proposes a bold, structural approach: reducing the costs associated with formal hiring. He suggests that the state should consider assuming a portion of the non-wage labor costs—a strategy successfully implemented in Colombia in 2012. By lowering the barrier to entry for firms to formalize their workforce, the government could catalyze a significant increase in the country’s potential growth rate.
"Peru has the fiscal space to evaluate measures of this type," Velandia argued. However, he cautioned that economic policy cannot function in a vacuum. The successful implementation of such a structural reform requires political willpower and the ability to build consensus across a fragmented political landscape.
Implications for the Future: Beyond 2028
The path to 4.5% growth in 2028 is clear, yet not guaranteed. The primary risks remain the intersection of political uncertainty and the potential for delayed structural reforms. Velandia pointedly remarked that Peru is currently not fully capitalizing on the favorable cycle of mineral prices. Instead of merely enjoying the windfall, he argues, these revenues should be aggressively funneled into productivity-enhancing investments—infrastructure, education, and technology—that elevate the nation’s total factor productivity.
The implication is clear: while El Niño is a formidable adversary for the coming winter months, it is a transient phenomenon. The real test for Peru lies in its ability to navigate its internal political volatility and address the structural inefficiencies that have plagued the economy for decades. If the government can maintain fiscal discipline, protect the most vulnerable during the climate crisis through targeted stimulus, and push forward with labor formalization, the country is well-positioned to exit its current cycle of stagnation and enter a period of sustained, high-level growth.
Ultimately, the Credicorp Capital report serves as both a warning and an invitation. It warns that the next five months will require careful management of resources and a proactive stance against environmental damage. Yet, it invites policymakers to look toward 2028 with confidence, provided that the foundational pillars of the economy—private investment and responsible monetary policy—are guarded against the erosive effects of political inaction.